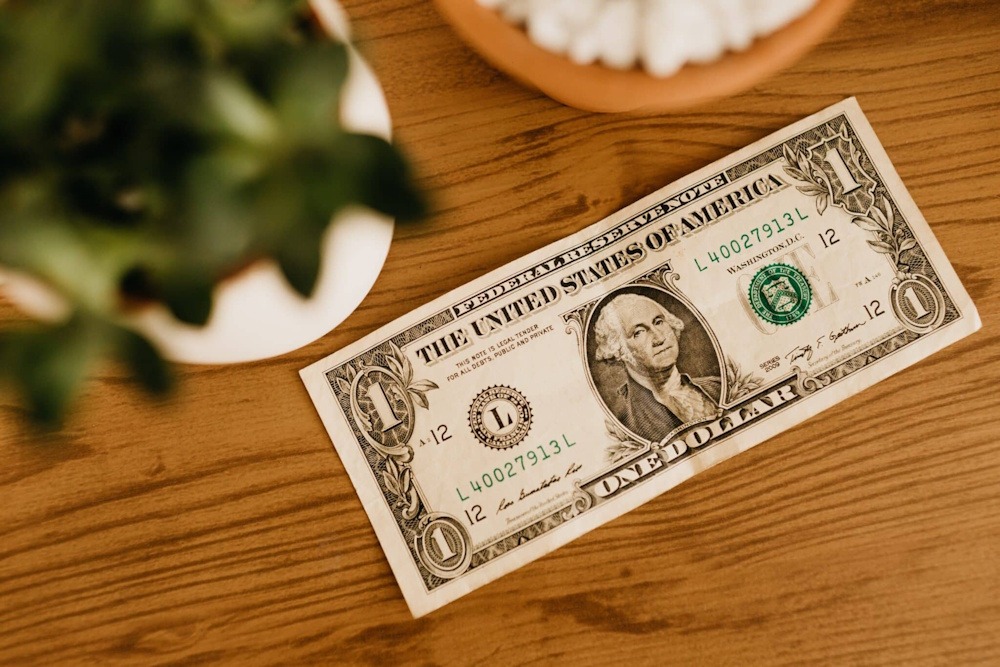
The dollar maintained its position at a two-month high on Thursday, following a robust manufacturing report that rekindled concerns over inflation and increased expectations for interest rate hikes. Additionally, a lacklustre Treasury auction resulted in rising yields across the curve, further bolstering the US currency. The broad dollar strength pushed the euro to $1.1378, a two-month low, while sterling languished near a three-month nadir at $1.3231. The dollar index, which measures the US currency against a basket of peers, remained close to a two-month high at 101.1. A stronger-than-expected purchasing managers’ report overnight fanned new price concerns, while a poorly received auction of five-year U.S. Treasury notes triggered a fresh round of bond selling.
As a result, five-year yields crossed 5% for the first time since 2007. The backdrop of rising inflationary risks and a robust economy suggests that the Federal Reserve is poised to implement additional rate hikes, as articulated by Governor Michael Barr on Wednesday. His remarks were interpreted by markets as a form of “forward guidance,” prompting traders to increase their positions on the likelihood of a second consecutive policy tightening in the upcoming month. “Given the relative strength of US growth and increasingly aggressive Fed rate-hike pricing, the US dollar continues to stand firm in its attraction to own,” said Chris Weston.
Signs that the US economy may be overheating are now firmly in focus, and policymakers may need to tighten further if inflation continues to surprise on the upside, he said. Inflation risks were further heightened by a nearly 4% increase in oil prices on Wednesday, following Iran’s president’s declaration of unwavering resistance. Concurrently, markets were assessing the implications of US President Donald Trump’s diesel export ban. Traders currently perceive a nearly 70% likelihood of an additional increase during the upcoming meeting of the US central bank in October, as indicated by CME Group’s FedWatch Tool, a rise from the 50% probability noted just a week prior. At 157.9, the Japanese yen remained close to its three-week low, with traders vigilant for potential intervention following the market’s assessment of the Bank of Japan’s recent rate hike to a 31-year high as lacking in hawkishness.
Data released on Thursday indicated that Japan’s manufacturing activity experienced a deceleration in September compared to the prior month, as both output and new orders exhibited signs of weakening. The Australian dollar fetched $0.7035, down 0.07% ahead of the latest jobs data, while the kiwi traded flat at $0.5676. Elsewhere, the offshore yuan traded flat at 6.7119 per dollar, as markets observed Chinese President Xi Jinping’s first US visit in three years, a high-stakes meeting poised to assess relations amid ongoing tensions surrounding trade, technology, Taiwan, and Tehran.