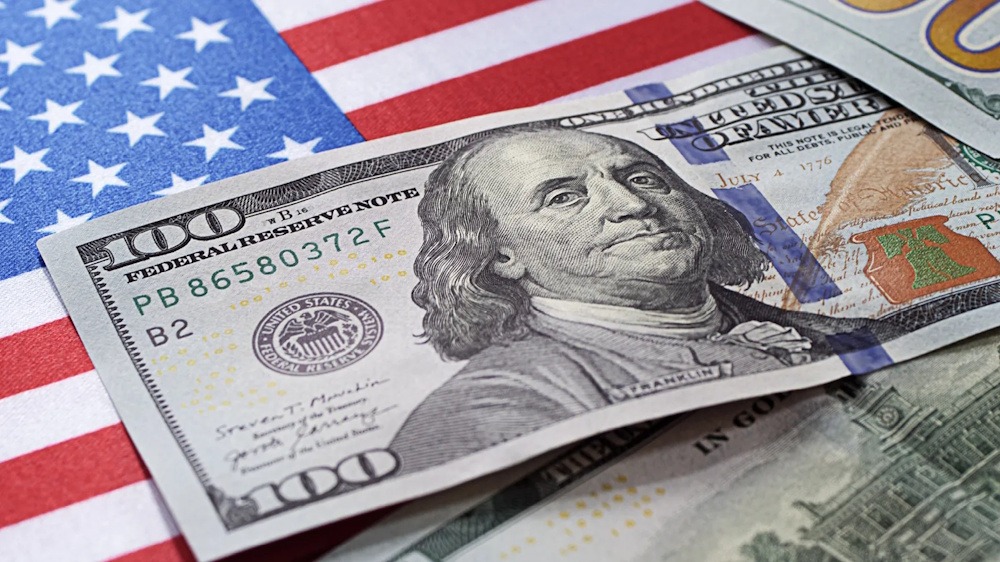
The dollar maintained its position close to its strongest level in a year and a half during early Asian trading on Monday, as a rising Middle East conflict prompted caution among investors ahead of significant US inflation data later this week that is expected to impact monetary policy. Oil prices fluctuated, experiencing both gains and losses, as Yemen’s Iran-backed Houthis intensified their strikes on Saudi Arabia, coinciding with the weekend attacks on two tankers. Prices were also influenced by the announcement from US President Donald Trump regarding an energy ceasefire between Ukraine and Russia on Sunday. Brent crude futures experienced a decline of 1%, trading at $103.55 per barrel during the Asian trading session. The dollar index, which measures the greenback’s strength against a basket of six currencies, was slightly down at 102.14 but remained not far from the 18-month peak it scaled last week. Trading remained within a narrow band as Japanese markets were closed for a holiday, resulting in reduced liquidity throughout the region. “We expect the Houthis to continue their attacks on Saudi Arabian energy assets, supporting gains in the oil price and the USD,” analysts said in a note.
They noted that although Iran had acknowledged the receipt of a US peace proposal via intermediaries, “we do not expect a breakthrough this week.” Against the yen, the US dollar experienced a decline of 0.14%, settling at 158.160 yen. The Australian dollar and its kiwi counterpart were both approximately unchanged at $0.6988 and $0.5614, respectively. Beyond the geopolitical backdrop, the market’s attention shifts to Wednesday’s US consumer price index report, which stands as one of the final significant economic releases prior to the Federal Reserve’s late-October meeting regarding interest rates. Data from last week indicated that US consumer sentiment declined further in early October, as the escalating cost of living due to the Middle East conflict negatively impacted households’ perceptions of the economy. The Fed raised rates last month for the first time since 2023 to rein in inflation, with markets closely monitoring economic data to assess the likelihood of further actions by policymakers.
Traders are currently assigning an 81% probability to the Federal Reserve maintaining its current stance this month, a notable increase from the 51% observed a month prior, as indicated by the CME FedWatch tool. Barclays analysts indicated that the dollar’s rally may be poised for a pause in the near term, with a potential pullback on the horizon. It was noted that significant fluctuations in bond markets have led to a tightening of global financial conditions, potentially encouraging Federal Reserve officials to adopt a more reassuring stance as they approach the October meeting, especially if the Consumer Price Index reading is subdued. Recent significant selloffs in bond markets have heightened investor concerns, as borrowing costs worldwide have surged to levels not seen in decades.
This rise is driven by apprehensions regarding inflation, escalating energy prices, and increasing government debt. The euro was up nearly 0.1% at $1.121, following a fifth consecutive week of losses as the common currency faced significant pressure from investor concerns regarding France’s fiscal health amid political uncertainty leading up to the 2027 presidential election. “It is still too early to tell whether higher borrowing costs will be sufficient to impose greater fiscal discipline on the French government,” said strategists. “We expect EURUSD to consolidate as the intensity of French fiscal and political headlines is unlikely to be sustained,” they said in a note, adding any rally in the euro is likely to be capped by Europe’s structural challenges. The British pound exhibited minimal fluctuation, remaining at $1.3245. In offshore trade, the US dollar remained unchanged against the Chinese yuan, standing at 6.6927 yuan.